Fresh August data from Pennsylvania, Virginia and Tennessee shows a US gambling market moving in several directions at once, with online casino revenue holding up better than some retail segments while sports betting activity continues to expand.
Pennsylvania’s Headline Decline Hides an Online Casino Gain
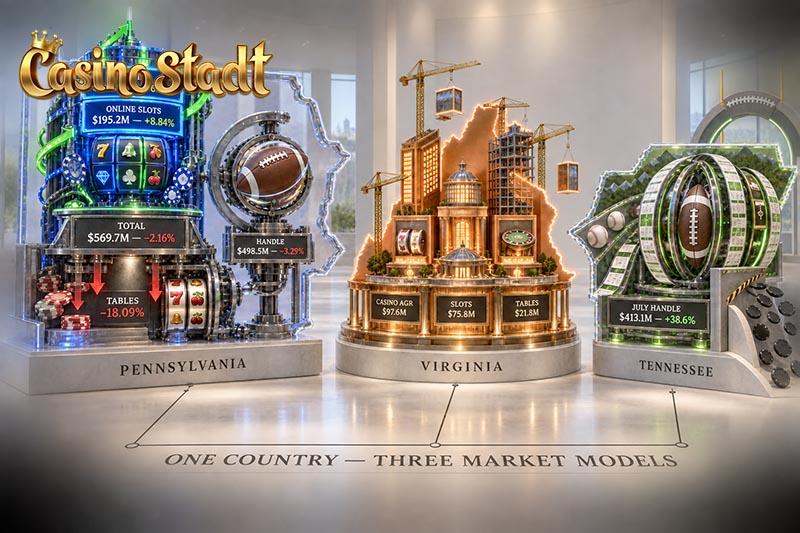
Pennsylvania’s total gaming revenue slipped 2.16% year over year in August 2026 to $569.7 million, reversing the 5.99% annual increase recorded in July.
Online casino revenue reached $245.7 million, up 6.25% from August 2025. Online slots did most of the heavy lifting, climbing 8.84% to $195.2 million. Retail slots, by comparison, fell 1.26%, while retail table-game revenue dropped 18.09%.
Sports betting was another weak spot. Pennsylvania sportsbooks handled $498.5 million, down 3.29% year over year, while taxable sports wagering revenue fell nearly 20% to $39.4 million.
For online casino players, the takeaway is fairly straightforward: Pennsylvania’s overall decline was not being driven by iGaming. Internet casinos continued to grow even while several retail and betting categories moved backward.
Virginia’s Casino Expansion Keeps Feeding Revenue
Virginia presented almost the opposite picture. The state’s five casinos generated roughly $97.6 million in adjusted gaming revenue during August, with $75.8 million coming from slots and about $21.8 million from table games.
Caesars Virginia remained the largest contributor at about $33.1 million, followed by Rivers Casino Portsmouth at $26.1 million and Hard Rock Bristol at $22.9 million. Live! Virginia in Petersburg added around $14.3 million, while Norfolk’s temporary casino generated about $1.1 million.
The month was weaker than July, when statewide casino AGR reached about $102.5 million, but Virginia’s longer-term direction is still being shaped by expansion. State casino revenue rose about 32% during 2025 to roughly $969.1 million, helped by newer properties and additional operating capacity.
That makes Virginia a different animal from Pennsylvania. Pennsylvania is a mature market where online gambling is taking a larger share of the action. Virginia is still adding casinos and building out a relatively young land-based industry.
Tennessee Keeps Growing Through the Summer Lull
Tennessee provides another useful comparison because its regulated market is sports betting only.
July 2026 wagers reached roughly $413.1 million, up 38.6% from July 2025. Adjusted taxable handle was about $410.2 million, generating roughly $7.6 million in privilege tax.
That growth came during what is normally one of the quieter periods on the US sports calendar. August typically starts the climb toward football season, with NFL preseason, college football futures and the late stages of the MLB season adding more betting opportunities.
Tennessee regulators have also been active on the enforcement side, ordering unlicensed offshore sportsbooks to stop serving customers in the state.
For bettors, that matters almost as much as the headline handle numbers. The state is drawing a harder line between licensed sportsbooks, which operate under local consumer-protection rules, and offshore operators outside that framework.
Online Casino Revenue Is Becoming Harder to Ignore
The broader trend across these markets is not simply that gambling is growing. The picture is more fragmented.
Pennsylvania shows online casino revenue expanding while several traditional casino categories retreat. Virginia is still benefiting from physical casino expansion. Tennessee is seeing sports betting volumes rise even before the busiest football months arrive.
For operators, that means growth increasingly depends on what products a state actually permits. Pennsylvania can draw revenue from online slots, online tables, poker, sportsbooks and retail casinos. Tennessee relies almost entirely on mobile sports betting. Virginia remains centered on physical casinos, although its market is still developing.
For the average player, those regulatory differences determine far more than the state revenue total. They affect which games are available, how many brands compete for customers and where operators are most likely to spend on bonuses and promotions.
The Bigger Story Is a Shift in Where Americans Gamble
August’s numbers also reinforce a trend that has been visible for some time: digital gambling can keep growing even when casino floors have a quieter month.
Pennsylvania is the clearest example. Online casino revenue rose more than 6% despite total statewide gaming revenue falling, while retail table games were down more than 18%.
Virginia currently sits on the other side of that divide because its casino industry is still expanding through new physical properties. Tennessee offers a third model altogether, with wagering conducted through an online-only sportsbook market.
Rather than one national gambling trend, the US gambling market continues to operate as a collection of very different state markets. August 2026 made that especially clear: online casinos grew in Pennsylvania, Virginia casinos remained near the $100 million monthly mark, and Tennessee sports betting continued to build from its summer low point.